


Moving the cliff edge: navigating a broken business rates system
The UK Chancellor has announced key changes to business rates, but Chris Grose at Hartnell Taylor Cook argues there’s still work left to be done to unburden Britain’s High Streets
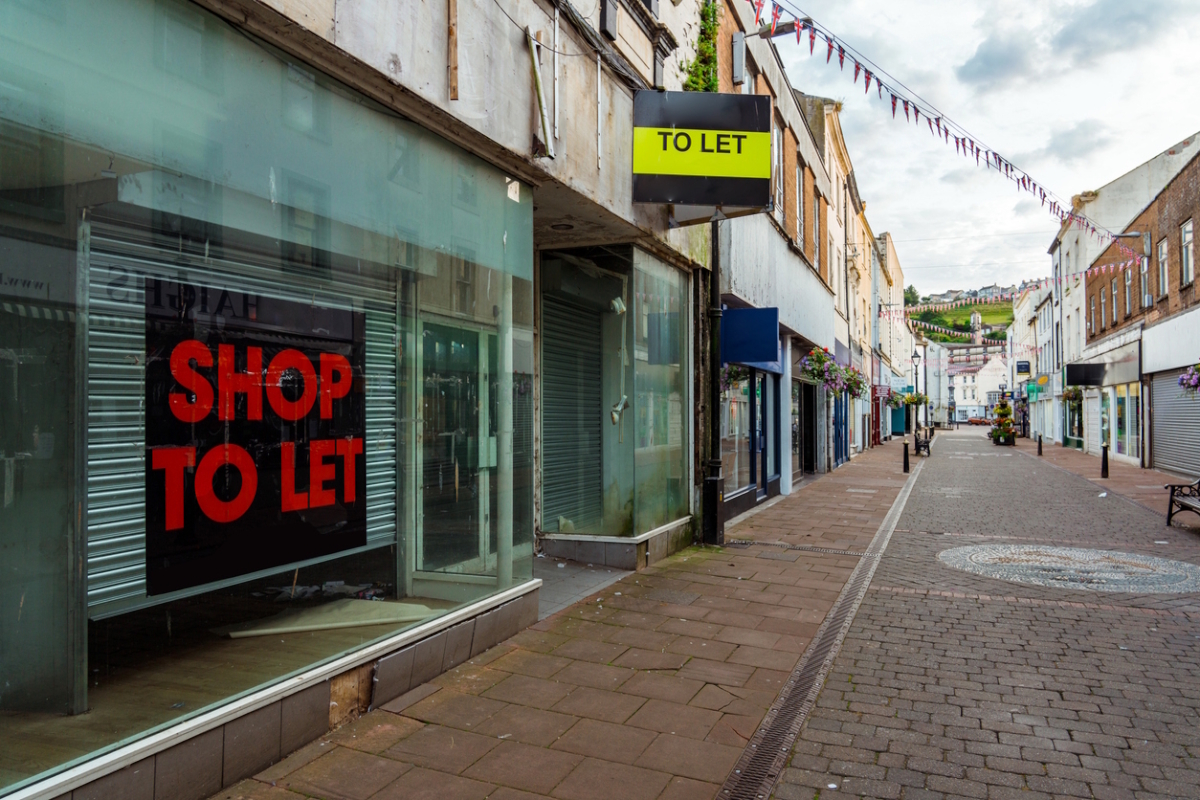
At the recent budget, the Chancellor delivered the latest update on business rates. It was yet more dancing around the actual problem: the system itself, not just some of the layers built up around it, is broken. Only some business owners will feel the weight of their rates lifted. Others will be left facing how to make do with what sorely needs mending.
What changed?
The most notable change came in the form of an exemption. The threshold for small business rates relief for retail, hospitality, and leisure has increased from £12,000 to £18,000, a move that should mean 70,000 businesses get to go forward rate free. Alongside this came mention of an extension of the transitional relief supplement for a further two years to help pay for these relief changes. There will also now be a clampdown on loopholes that allow online businesses to avoid paying tax, hopefully adding to the tax take and thus helping with the threshold increase.
But although change is welcome, especially if it benefits small businesses, it is vital to acknowledge the limitations of these changes and seriously consider whether it would have been better for business if the government refocused its attention.
Taking the heat off one business only means shifting it elsewhere. The cliff edge only moves forward; it doesn’t completely disappear. Repairing the rates system so it is fairer on businesses requires more than continual tinkering. This has proven ineffectual. There needs to be a complete re-evaluation of how the system is set up, foundationally, and an active effort to uproot fundamental issues, not just keep tending to top-layer soil.
A rates overhaul is the overall goal, but there is a meantime in which businesses will still need to navigate a tricky landscape. That means understanding clearly what policy changes matter to them and, equally as important, whether they could be saving any money under the existing regime.
The reality of rates reform
To begin with, though freezing rates and increasing the threshold may initially sound promising, it falls short if you look just below the surface. The new rules just pass on the baton of burden, triggering a larger jump in bills once values pass the new £18,000 threshold.
Relief for one business is a problem magnified for another. The rate in the pound for small retail and hospitality properties is already lower than it was in 1991 and, perhaps more difficult to swallow, lower rate payments may just result in higher rents. There is always a push and pull in the current system, and that’s why it needs reconfiguring.
Reliefs must be reviewed or even withdrawn. This should be in place of making changes that only delay the inevitable. It must be acknowledged that business rates returns are fixed, meaning if one person pays less, then another must pay more.
What is there to do?
It is not, however, about doing away with rates entirely. No one wants to take on more tax to replace the income business rates brings in for the government, so it is something businesses do have to deal with, whether in one form or another.
Ratepayers and their representatives have called for more frequent valuations, a lower rate in the pound, and a balance between retail and non-retail properties. But when calls are only partly or not at all answered, the immediate challenge is to reduce rates liability where possible.
Paying right
It is important that businesses check that rates are only being paid on properties that they are liable for. It is also crucial to check whether the rateable value is correct and, if it isn’t, have the confidence to appeal if necessary. This can be an expensive and time-consuming administrative burden, but it is always worth considering.
And consideration pays. There can be reliefs that businesses are eligible for that they aren’t actually aware of, so carefully checking this and applying is a helpful step. This said, the Budget has proved to be bad news for landlords or those with empty property who will have no way to mitigate payment of empty rate.
The three or six month empty relief window is insufficient to fettle a property ready for letting, market it and process the legals, and that assumes the relief isn’t taken by the outgoing ratepayer. The empty relief should have been reviewed as the current scheme does not work and is far too much of a burden on landlords and others affected who generally don’t want their properties vacant.
Aligning on values
Rateable values are meant to represent the open market rental value at the relevant valuation date, which is currently 1 April 2024. There will be a revaluation in 2029 with a valuation date in April 2027. As rental agreements are followed by changes in rateable values, businesses must try to keep their rental agreements as low as possible from the outset to steer clear of a surge in costs later.
Taxation change
Starting afresh on the property tax system would help redress some obvious problems. In the residential sector, for instance, where council tax is in dire need of revaluation, greater fairness for smaller businesses might be found.
While the mansion tax surcharge may go some way in helping, high-value residential properties have often been paying less than their fair share, leaving businesses to pick up the slack through rates. The government must commit to a fundamental redesign of property taxes from the ground up to fix the system once and for all.
Looking forward
The government must return to the drawing board. The current system is not built for today’s economic reality, and businesses are feeling the pressure of it. Rateable values, the rate in the pound, and their relationship to the market are not what they were in 1990.
The current system means businesses will have challenging times ahead, but if there is a silver lining, it is that businesses do not lack the ability to at least challenge the status quo and play their part in the push for change.
Chris Grose is Senior Vice President of the IRRV and Rating Director at Hartnell Taylor Cook
Main image courtesy of iStockPhoto.com and CHUNYIP WONG
Related Content
Supply Chain Talk
view all
Humans, AI and robots - Who will lead the supply chain of tomorrow?
From Retail AI Ambition to Retail AI at Scale
Winston House, 3rd Floor,
Units 306-309, 2-4 Dollis park,
London, N3 1HF
020 8349 4363
© 2026, Lyonsdown Limited. teiss® is a registered trademark of Lyonsdown Ltd. VAT registration number: 830519543