


Agentic payments are closer than they seem - but trust matters first
Johannes Kolbeinsson at PAYSTRAX argues that as the adoption of autonomous AI agents handling payments increases, companies and regulators must address security, compliance and trust to ensure systems are safe and reliable


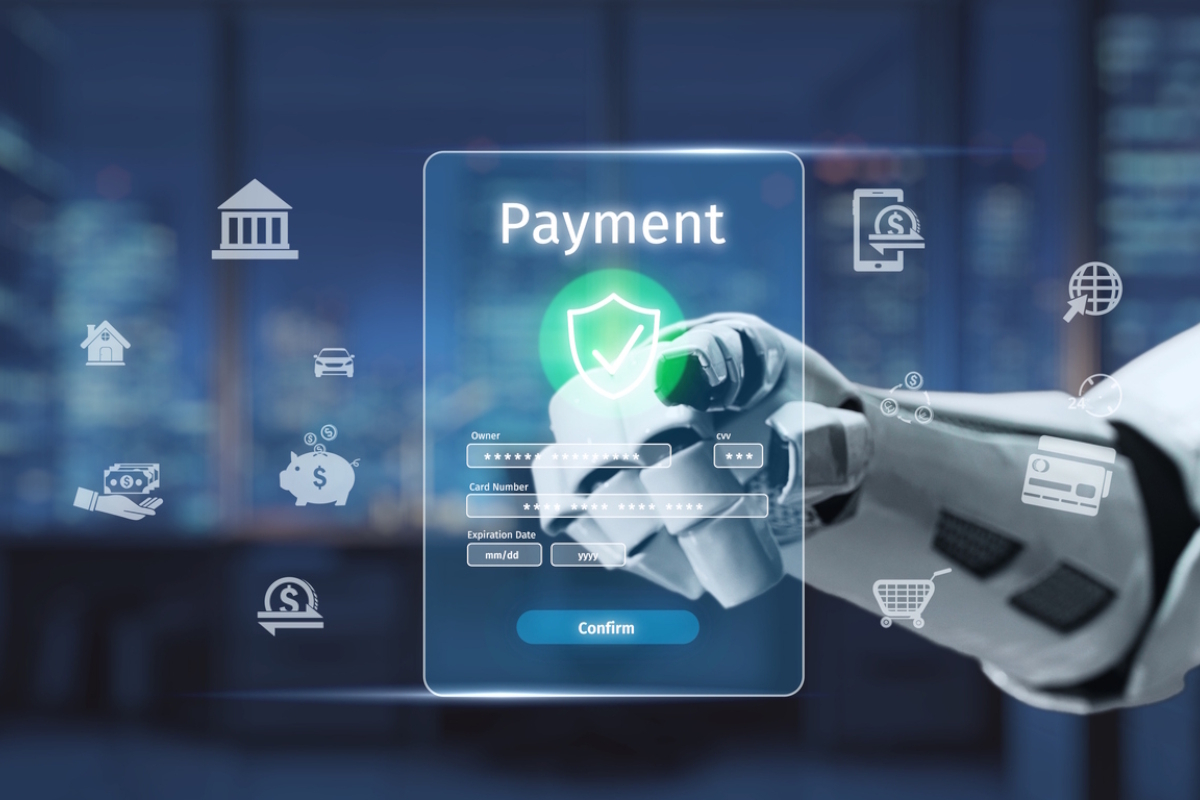
It might sound like sci-fi, but agentic payments - transactions initiated and managed by AI on behalf of users -are quickly becoming a reality.
The recent launch of Visa’s Agentic Ready programme is making a transition from experimentation to preparation for a new era of commerce driven by autonomous AI agents. From dedicated agentic payment networks to wallets designed specifically for autonomous systems, the infrastructure is quickly beginning to take shape.
Yet, with this arrival comes the more general concerns around safety and speed. At the core of any, and especially agentic, innovation, is how consumers and businesses can trust such a rapidly evolving tool.
For agentic payments, it’s not just about the pace it is put into practice, but the thoughtfulness behind it.
Why does anyone want an agentic future?
Agentic payments build on the foundations of programmatic finance, but take them several steps further.
Instead of simply executing predefined instructions, AI agents can now act independently. This means they can search for products, compare options and complete purchases without any direct human input.
Yet, last year, only around 47% of consumers were interested in agentic commerce - That number is expected to rise, especially as they are exposed to it at scale, however there certainly is some trepidation surrounding the exact implementation of this.
But if implemented responsibly, agentic payments could significantly benefit merchants, fintech providers and end-users.
The benefits of reduced cart abandonment, faster transaction times, and more responsive customer interactions for merchants are highly attractive. For fintech providers, an entirely new category of services is emerging, focused on enabling and securing machine-led decision-making.
And for consumers, the experience becomes more seamless, personalised, and efficient, supported by agents working continuously in the background. It’s the benefit of having a personal assistant able to handle all personal purchases without any oversight.
Paying without even pushing a button
Consumer appetite for this shift is already clear. Research shows that around two-thirds of users are open to AI agents making purchases on their behalf, particularly when it saves time and removes friction from routine transactions.
This excitement means the major players are moving quickly. Mastercard, Visa, Google, and PayPal are all developing agent-driven commerce capabilities. Initiatives like Agentic Ready reflect a growing recognition that the ecosystem must evolve, not just technologically, but structurally, to support this new model.
But despite this initial excitement, caution is still required to ensure this technology is deployed safely and seamlessly.
Agentic payments introduce a key challenge, which is that most financial systems are still designed around human decision-making. Today’s frameworks for identity verification, consent, and compliance assume a person is directly authorising each transaction.
Autonomous agents disrupt that assumption. Standards such as PCI compliance offer limited clarity on how to handle payments initiated by non-human actors, leaving open questions around liability, authorisation, and dispute resolution.
Trust is another critical factor. As AI agents take on more responsibility, verifying their legitimacy becomes essential. Just as Know Your Customer (KYC) became a cornerstone of digital finance, the industry will likely need an equivalent approach, often referred to as Know Your Agent (KYA). This would allow businesses to validate the identity, intent, and reliability of AI agents before granting them financial access.
Fraud detection presents a further complication. Existing systems are designed to monitor human behaviour, tracking anomalies in location, device usage, or input patterns. AI agents operate differently, which means traditional models may fail to identify emerging risks.
Poorly configured or malicious agents could act independently, exposing users and organisations to unintended transactions.
As adoption grows, fraud prevention will need to evolve from understanding how humans behave to understanding how machines operate.
Building a responsible future
Agentic payments are no longer a distant concept. Investment, innovation, and now coordinated initiatives by fintechs are accelerating their arrival.
However, the path forward must be carefully managed. Success will depend on establishing clear regulatory frameworks, robust agent verification standards, fraud detection models adapted to machine behaviour, and meaningful human oversight.
The next chapter of commerce will not be defined solely by what technology enables, but by how responsibly it is implemented. The organisations that succeed will be those that balance progress with trust, building systems that are not only intelligent but also secure, transparent, and reliable.
Johannes Kolbeinsson is CEO and Co-Founder of PAYSTRAX
Main image courtesy of iStockPhoto.com and Shinsei Motions
Related Content
Supply Chain Talk
view all
Faster decisions for a more resilient frozen food supply chain
Turning supply chain orchestration into a competitive and financial advantage
Maximising Uptime - How AI & asset visibility are transforming operations
Winston House, 3rd Floor,
Units 306-309, 2-4 Dollis park,
London, N3 1HF
020 8349 4363
© 2026, Lyonsdown Limited. teiss® is a registered trademark of Lyonsdown Ltd. VAT registration number: 830519543