


Why indecision can be more damaging than making the wrong call
Leaders can make consequential decisions even when information is incomplete. Paul Oberschneider at Hilltop Capital Partners argues that while the risks of doing this are real, waiting for certainty can carry its own costs


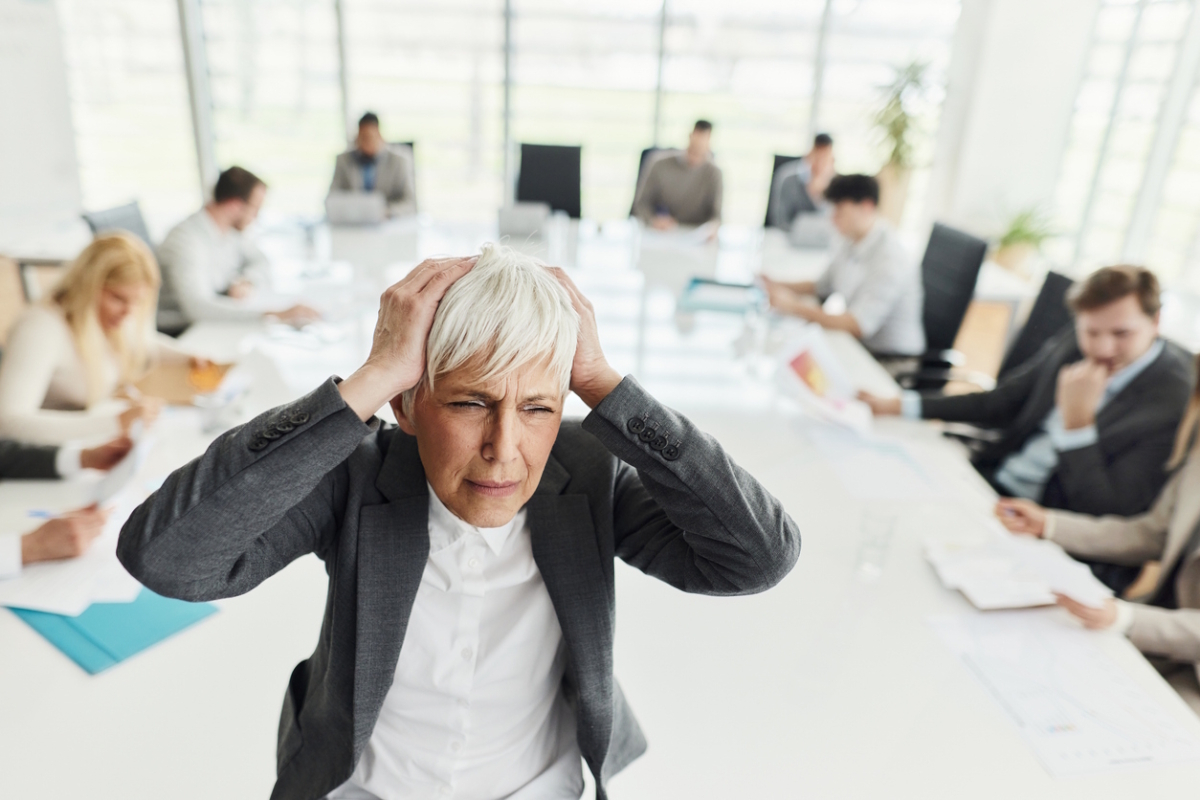
The greatest risk in business is not always making the wrong decision. Sometimes it is failing to make one at all.
I’ve spent much of my working life making decisions without knowing how they would turn out.
I’ve built businesses across emerging markets, navigated financial crises, sold companies, lost fortunes and started again. Some decisions proved extraordinarily successful. Others were painfully expensive.
But looking back over more than three decades as an entrepreneur, I’ve come to believe that some of the most damaging decisions were the ones I never made.
The opportunities I hesitated over. The conversations I postponed. The moments when I knew something needed to change but convinced myself that waiting a little longer was the sensible thing to do.
In business, we spend enormous amounts of time analysing the consequences of getting something wrong. We devote considerably less attention to the consequences of doing nothing.
And yet indecision has a cost. It just doesn’t always appear on a balance sheet.
The Illusion of Certainty
When I began building my property business in Estonia in the 1990s, there was no established playbook.
The country was emerging from decades of Soviet rule. Property markets were being created almost from scratch. Reliable information was scarce, institutions were evolving and the rules of business were changing around us.
Had I waited for complete information, predictable regulation and certainty about the future, I would probably never have started. Instead, I made decisions based on what I could see, what I understood and, importantly, what I was prepared to risk.
We eventually expanded across seven countries, building a substantial property advisory business in Central and Eastern Europe.
Were all those decisions correct? Absolutely not.
We made mistakes. We misjudged people, markets and opportunities. But we learned, adjusted and kept moving.
One of the advantages of being an entrepreneur in an emerging market was that you quickly discovered something that remains true in every boardroom today.
Certainty is rarely available when the most important decisions need to be made.
By the time everyone agrees an opportunity is obvious, much of its value may already have disappeared.
The Hidden Cost of Waiting
Indecision is particularly dangerous because it often looks responsible.
A CEO asks for another report. A board commissions another review. An investment committee requests additional analysis. Sometimes these are entirely appropriate responses. There are decisions where patience and further investigation are essential.
But there is a difference between gathering information to improve a decision and gathering information to avoid making one. I’ve sat in meetings where everyone around the table understood what needed to happen. The problem wasn’t a lack of information. It was a reluctance to accept responsibility for the consequences. Nobody wanted to be the person who made the wrong call. So nothing happened.
Meanwhile, competitors moved, opportunities disappeared and problems that might have been manageable became considerably more expensive. The trouble with indecision is that it creates the illusion of safety. You haven’t committed capital. You haven’t changed strategy. You haven’t upset anyone. But standing still is itself a decision, and the market doesn’t stand still with you.
When Being Right Isn’t Enough
I sold my business before the global financial crisis of 2008. From a financial perspective, the timing was extraordinarily fortunate. I had spent nearly two decades building an organisation, and I exited before the markets collapsed. It was the right decision.
But there was another decision embedded within it, one whose consequences I didn’t fully appreciate until much later. I didn’t simply sell the business. I walked away from the world I had spent twenty years building. The relationships, the network, the daily relevance, the position I occupied in the market. I left my chair. And the world moved on.
Others occupied that space. Opportunities continued without me. The network I had spent decades developing gradually lost its immediacy. I had made the right financial decision, but I had failed to make an equally important strategic one: what role did I want to play next?
I confused exiting a business with exiting an industry.
That experience taught me that the consequences of a decision are not always confined to the decision itself. Sometimes the greater damage comes from failing to consider what must happen immediately afterwards.
Knowing when to exit isn’t the same as knowing what to do next.
Fear Is Often Disguised as Analysis
As entrepreneurs become more successful, something interesting can happen. We become increasingly conscious of what we have to lose. Early in our careers, we often make decisions quickly because we have relatively little to protect. We trust our instincts, accept uncertainty and move forward.
Later, with wealth, reputation, employees and investors depending on us, the stakes become higher. That should make us more disciplined. But it can also make us fearful. We begin looking for guarantees where none exist.
I’ve experienced this myself, particularly after suffering significant financial setbacks. When you’ve made costly mistakes, it’s tempting to believe that the answer is to become more cautious about everything. But caution and paralysis are not the same thing. A bad experience should improve your judgment, not destroy your willingness to act. The challenge is learning to distinguish genuine risk assessment from fear masquerading as prudence.
Making Decisions Without All the Answers
Today, working in real estate finance and investment, I see how much emphasis is placed on data, due diligence and risk management. All are essential, particularly when managing other people’s capital. But information alone doesn’t make decisions. People do. And leadership ultimately requires judgment. I’ve developed a few principles over the years.
First, distinguish between reversible and irreversible decisions. Not every decision deserves the same level of scrutiny. Some can be tested, adjusted or abandoned relatively cheaply. Others involve permanent commitments of capital, reputation or strategic direction. Knowing the difference matters.
Second, establish what information would genuinely change your mind. If another month of analysis is unlikely to alter the conclusion, ask yourself what you’re really waiting for.
Third, understand the cost of doing nothing. Every investment proposal should consider the downside of proceeding. Far fewer properly quantify the opportunity cost of delay.
Finally, accept that accountability comes with leadership. You cannot eliminate uncertainty by passing a decision around a committee. At some point, someone has to take responsibility.
None of this means acting impulsively. In fact, the greater the potential consequences, the more important disciplined thinking becomes. But disciplined thinking should lead somewhere.
The Courage to Move Forward
At this stage of my career, I no longer believe good leadership is about always being right.
I’ve been right about markets and wrong about people. I’ve made excellent investment decisions and poor personal ones. I’ve acted too quickly at times and waited far too long at others.
The most valuable lesson has been recognising that making a decision is only the beginning. You need the humility to acknowledge when circumstances change, the discipline to correct course and the resilience to live with the consequences.
A wrong decision, recognised early, can often be corrected. Indecision, allowed to continue, quietly becomes a strategy of its own. And frequently a very expensive one. There is a phrase I return to increasingly often: you don’t need to see the entire staircase to take the next step.
In business, that doesn’t mean abandoning analysis or ignoring risk. It means accepting that no amount of preparation will remove uncertainty from the future. The responsibility of leadership is not to guarantee the outcome. It is to make the best decision possible with the information available, accept responsibility for it and remain willing to adapt.
Because in the end, the greatest mistake may not be choosing the wrong direction. It may be spending so long deciding which way to go that the opportunity to move has passed.
Paul Oberschneider is an entrepreneur, investor and author who leads Hilltop Capital Partners. His forthcoming book, Coming Clean: Confessions of an Entrepreneur, explores ambition, addiction, recovery and the true meaning of success
Main image courtesy of iStockPhoto.com and skynesher
Related Content
Supply Chain Talk
view all
Humans, AI and robots - Who will lead the supply chain of tomorrow?
From Retail AI Ambition to Retail AI at Scale
Winston House, 3rd Floor,
Units 306-309, 2-4 Dollis park,
London, N3 1HF
020 8349 4363
© 2026, Lyonsdown Limited. teiss® is a registered trademark of Lyonsdown Ltd. VAT registration number: 830519543